From double-licensing lawsuits to a 48% price cut: how Qilu repriced its TYK stake
Tracing 20 months of HKEX filings behind TYK Medicines' (02410.HK) HK$288.8m H-share placement at HK$3.80: from disputed 2025 Huiyu agency talks and RMB 300m settlement to Qilu's 48% repriced buy-in.
Twenty-four hours after TYK Medicines, Inc (HKEX: 02410) agreed to pay Sichuan Huiyu Pharmaceutical (SSE: 688553) RMB 300 million (approx. $41.5 million) to end a competing commercial-rights battle over lung-cancer drug Kadasa (TY-9591, deushenertinib mesylate), the pre-commercial biotech signed fresh subscription agreements late on November 12 to issue 76,000,000 new H-shares at HK$3.80 apiece for HK$288.8 million in gross proceeds (net HK$288.42 million, or approx. RMB 247.01 million / $34.3 million). Per TYK’s November 12 HKEX filing, TY-9591 licensee Qilu Pharmaceutical is taking 75% of the allotment alongside Hong Kong open-ended fund CVG Global, subject to CSRC filing and HKEX listing approval before a January 29, 2027 long-stop date.
Stepping back across 20 months of exchange filings shows how a boardroom tie, a disputed agency pact, and an immovable commercial launch clock gave Qilu the leverage to cut its entry price nearly in half.
How the deal unfolded: a 20-month chronology
| Date | Milestone in HKEX / SSE Filings | Commercial & Financial Consequence |
|---|---|---|
| Mar 27, 2025 | Ding Zhao resigns as non-executive director of TYK | Ding chairs and controls STAR Market drugmaker Sichuan Huiyu (SSE: 688553), leaving Huiyu a connected-person associate |
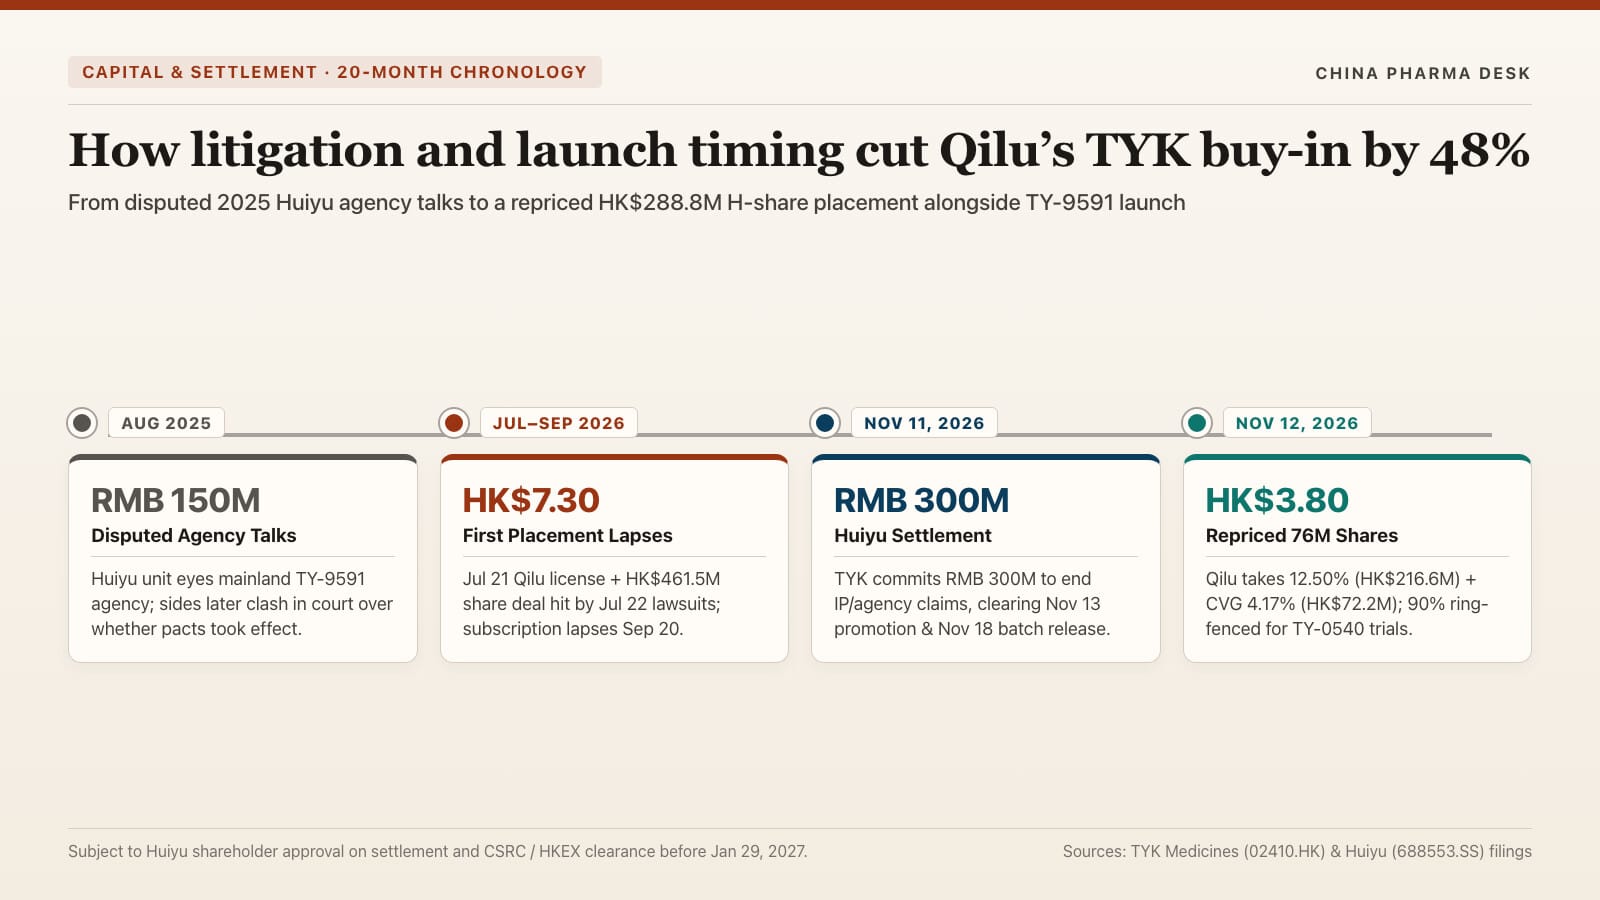
| Aug 26, 2025 | Huiyu & TYK disclose potential mainland general agency | Huiyu unit Sichuan Huichenxin eyes mainland distribution of TY-9591 for up to RMB 150m in initial milestones; parties later clash over whether binding contracts took effect |
| Jun 30, 2026 | TYK H1 2026 balance-sheet cutoff | Cash and equivalents sit at RMB 202 million with zero commercial product revenue ahead of launch |
| Jul 15, 2026 | Extraordinary general meeting approves 20% general mandate | Authorizes board to issue up to 76,013,163 new shares without another shareholder vote |
| Jul 21, 2026 | TYK signs exclusive Qilu license + HK$7.30 H-share deal | Qilu gets mainland rights to TY-9591 (RMB 300m cash upfront + up to RMB 2.06b milestones) and agrees to buy 63.22m H-shares at HK$7.30 (HK$461.53m / RMB 400m) |
| Jul 22, 2026 | TYK discloses competing Zhejiang & Sichuan lawsuits | One day after the Qilu deal, TYK sues in Changxing (Zhejiang) to void alleged Huiyu agency pacts; Huiyu countersues in Neijiang (Sichuan) to enforce them |
| Aug 20 & 27, 2026 | Placement extended; NMPA grants conditional approval | Share closing extended to Sept 20; NMPA clears TY-9591 first-line for EGFR-mutant NSCLC with CNS metastases, starting the launch clock |
| Sep 20, 2026 | HK$7.30 Qilu share subscription lapses | Amid litigation overhang and falling share prices, both sides let the HK$461.53m equity leg lapse while keeping the TY-9591 drug license alive |
| Nov 11, 2026 | TYK signs RMB 300m conditional settlement with Huiyu | Days before launch, TYK agrees to pay Huiyu RMB 300m in two tranches (matching Qilu’s upfront) to drop all claims; expects ~RMB 300m 2026 loss |
| Nov 12–13, 2026 | Repriced HK$3.80 placement signed; Qilu starts academic promotion | Qilu returns at HK$3.80 (HK$216.6m for 12.50%) alongside CVG Global (HK$72.2m for 4.17%); Qilu promotion begins Nov 13, first batch due Nov 18 |
Why TYK had to settle first—and why Qilu won on price
At the center of the dispute is Kadasa (TY-9591), a deuterated derivative of osimertinib engineered to curb toxic metabolite formation so clinicians can push exposure against brain metastases in EGFR exon 19 deletion or L858R non-small-cell lung cancer. Once NMPA granted conditional approval on August 27, delaying launch to fight prolonged court battles in Zhejiang and Sichuan would have forfeited TYK’s narrow commercial window against entrenched third-generation EGFR inhibitors osimertinib, aumolertinib, and furmonertinib.
Settling with Huiyu on November 11 cleared the title so Qilu could kick off hospital academic detailing on November 13, complete first commercial batch production around November 18, and ship to tier-one distributors before month-end. Yet the settlement’s price—RMB 150 million within 30 days of Huiyu shareholder approval and another RMB 150 million by January 25, 2027—effectively consumed the entire RMB 300 million upfront Qilu had agreed to pay for the drug.
Letting the July equity subscription lapse in September and waiting until the Huiyu cloud lifted transformed Qilu’s economics:
| Equity Deal Metric | Lapsed July 21, 2026 Subscription | Repriced November 12, 2026 Placement |
|---|---|---|
| Subscribers | Qilu (Anchor International) alone |
Qilu (57.0m shares) + CVG Global (19.0m shares) |
| Subscription price | HK$7.30 per share (13.3% discount to HK$8.42 close) | HK$3.80 per share (7.32% discount to HK$4.10 close; +6.32% vs. 5-day avg) |
| Qilu cash outlay | HK$461.53 million (approx. RMB 400.0m) | HK$216.60 million (HK$244.93m less cash; 47.9% lower price) |
| Qilu post-close stake & lock-up | 14.26% enlarged capital; 6-month lock-up | 12.50% enlarged capital (substantial shareholder); 6-month lock-up |
| Co-investor terms | None | CVG Global takes 4.17% (HK$72.20m) with zero lock-up |
| Total net proceeds to TYK | HK$460.54 million (approx. RMB 399.14m) | HK$288.42 million (approx. RMB 247.01m) |
Follow the cash: ring-fenced pipeline money vs. settlement outflows
Reading the November 11 and November 12 filings together clarifies how three separate pools of money move across TYK’s accounts:
- The settlement washes out the license upfront: TYK’s RMB 300 million obligation to Huiyu is funded out of operating liquidity—principally its RMB 202 million mid-year cash reserve and cash receipts from Qilu’s RMB 300 million TY-9591 upfront and early supply payments.
- New H-share proceeds are locked onto TY-0540, not Huiyu: TYK cannot legally divert the bulk of the HK$288.42 million placement to pay Huiyu. The filing ring-fences 90% of net proceeds for CDK2/4/6 inhibitor TY-0540—60% (
HK$173.05 million) for Phase 2/3 monotherapy trials in platinum-resistant ovarian cancer and 30% (HK$86.53 million) for Phase 2/3 fulvestrant-combination studies in CDK4/6-resistant breast cancer—leaving only 10% (HK$28.84 million) for general working capital. Practically, the equity raise backfills R&D funding that TYK can no longer spare from its internal treasury. - Mandate ceiling and unlocked float: Issuing 76,000,000 shares uses almost every share permitted under July’s 20% general mandate (
76,013,163shares), leaving just 13,163 shares on the shelf and diluting core insiders led by Chairman Wu Yusheng from 40.11% to 33.43%. Because the Qilu and CVG Global agreements are not inter-conditional—and CVG Global’s 19 million shares carry no disposal lock-up—secondary-market traders will watch post-listing liquidity alongside Qilu’s six-month lock-up.
Next evidence triggers
Four dated checkpoints govern execution from here: first commercial batch completion around November 18 and distributor shipments by late November 2026; Huiyu’s extraordinary general meeting vote to activate the settlement and trigger Sichuan court withdrawal; CSRC filing completion and HKEX listing approval before the January 29, 2027 placement long-stop date; and the second RMB 150 million settlement installment due by January 25, 2027.
Related on China Pharma Desk: TYK is paying RMB 300 million so Qilu can sell a drug Huiyu says it already had · Qilu registers Phase 3 myeloma trial for BCMA/GPRC5D trispecific QLS4131 · Qilu registers Phase 3 ovarian cancer trial for Claudin6 ADC QLS5132