Charles River’s $470m Frontage purchase hinges on a take-private and a split
The proposed deal would take Frontage private before allocating its businesses to Charles River, Tigermed and Song Li. The $470m price covers the target operations.
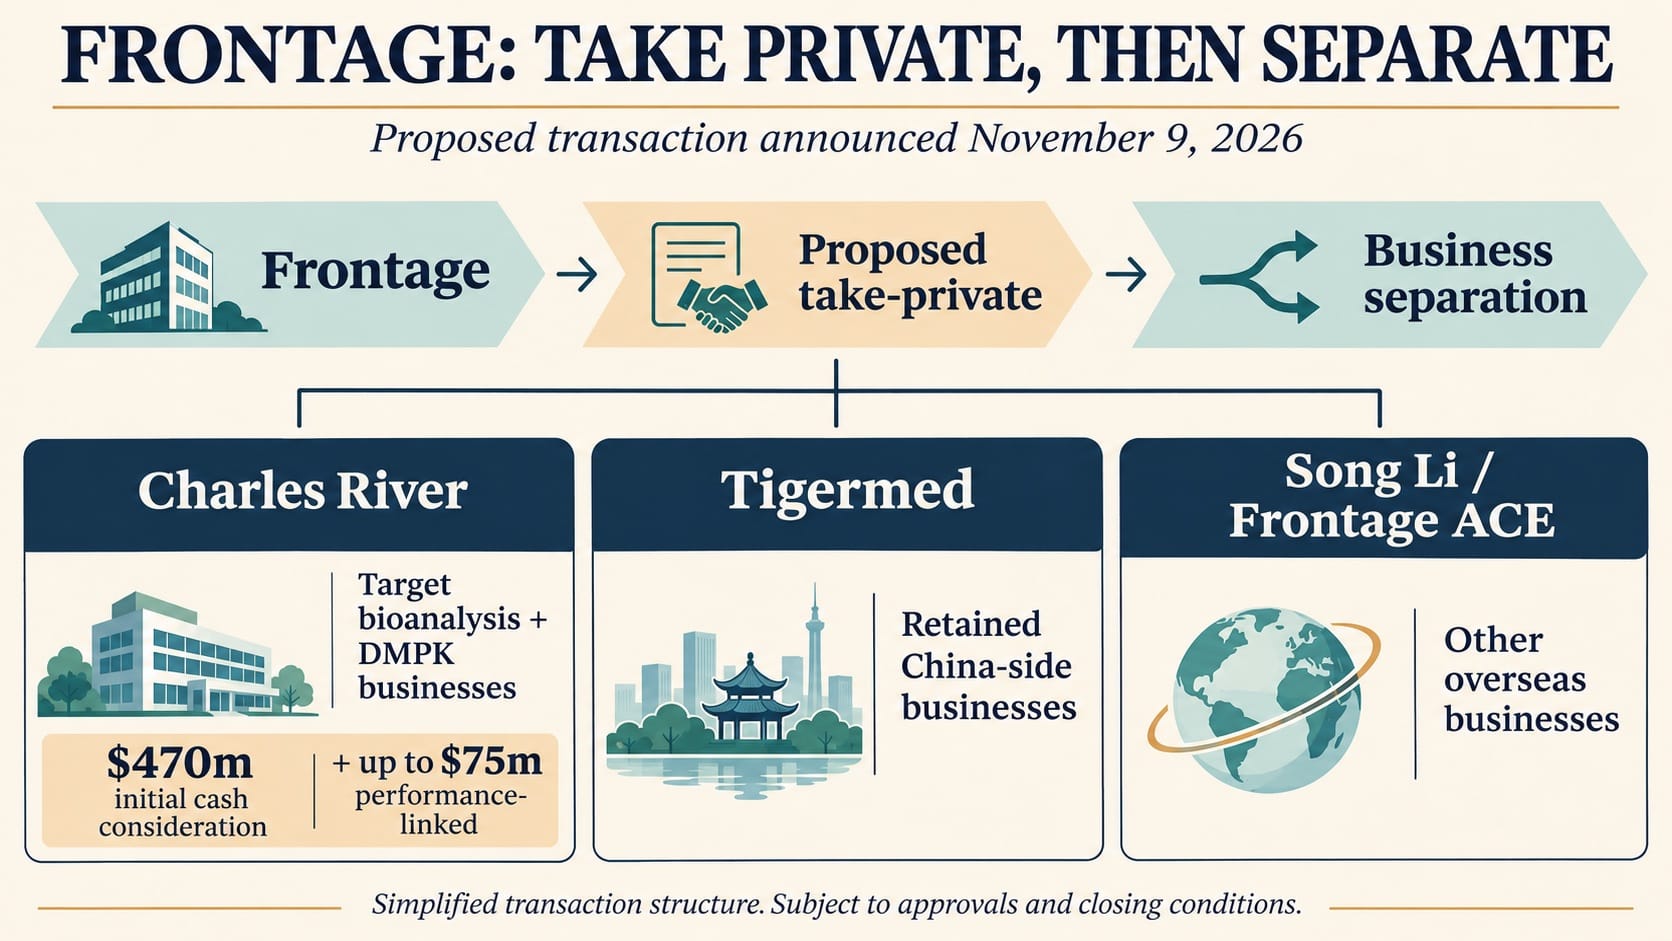
Charles River’s proposed purchase of Frontage’s bioanalysis and drug metabolism and pharmacokinetics (DMPK) operations would reshape a Chinese-controlled research-services group through two linked steps: privatization, followed by a division of its businesses among three owners.
The deal, announced on November 9, puts an initial cash price of about $470 million on the target operations in Exton, Pennsylvania, with up to $75 million more tied to performance. That headline amount describes Charles River’s intended business purchase, rather than a valuation for all of Frontage’s operations.
Three destinations for one listed group
Frontage’s joint announcement filed with the Hong Kong exchange sets out a proposed take-private through SanRex, the consortium vehicle. The scheme includes a cancellation price of HK$2.370 per scheme share and a separate, conditional earnout arrangement. Withdrawal of Frontage’s Hong Kong listing would follow the scheme becoming effective.
The subsequent restructuring would allocate the target bioanalysis and DMPK business to Charles River, the defined China-side business package to Tigermed, and other overseas businesses to chairman Song Li’s Frontage ACE. The allocation follows specified legal entities and assets; it is more detailed than a simple division along national borders.
For overseas readers tracking China’s contract research organizations, the relevant question is therefore which business changes hands at each stage. Participation in the take-private does not mean the consortium members will continue to own an undivided Frontage together.
Tigermed’s domestic focus, Charles River’s clinical expansion
In its November 9 disclosure, Tigermed said the transaction would help it focus on its clinical CRO business and deepen its presence in China. It reported holding 64.48% of Frontage before the transaction. After completion, it would cease holding Frontage shares while retaining the specified China-side businesses.
That is a narrower proposition than keeping control of the listed group while selling a laboratory unit. For readers evaluating Tigermed’s future operating footprint, the retained businesses and the resulting ownership structure matter alongside the cash proceeds.
Charles River, meanwhile, is buying additional clinical-testing capacity. Its announcement, furnished to the US Securities and Exchange Commission, identifies two Exton sites with approximately 340 employees. It says clinical-phase testing currently accounts for about 15% of its bioanalysis revenue, whereas most of Frontage’s bioanalysis revenue came from clinical development in 2025.
The businesses thus fit different stated priorities: Charles River seeks broader support across development stages; Tigermed is concentrating its retained portfolio around its China strategy. Neither rationale establishes that integration or separation will be straightforward.
Charles River expects closing in the first half of 2027. Shareholder, regulatory and court approvals remain part of the proposed transaction’s conditions. The assets have not already changed hands, and the additional $75 million is contingent—not guaranteed cash at closing.
Prepared by China Pharma Desk using AI-assisted research and writing. Factual claims were checked against the linked company disclosures; interpretation is the Desk’s analysis. The illustration simplifies the proposed structure.
Industry information only—not medical or investment advice.