Betta wins EU approval for ALK inhibitor Gevalka across two lines as Q3 turns loss-making
Betta Pharmaceuticals (SZSE: 300558) won European Commission approval (EU/1/26/2078) for Gevalka (ensartinib) in 1L and post-crizotinib ALK+ NSCLC via SFL Pharmaceuticals amid a RMB 44.4m Q3 loss.
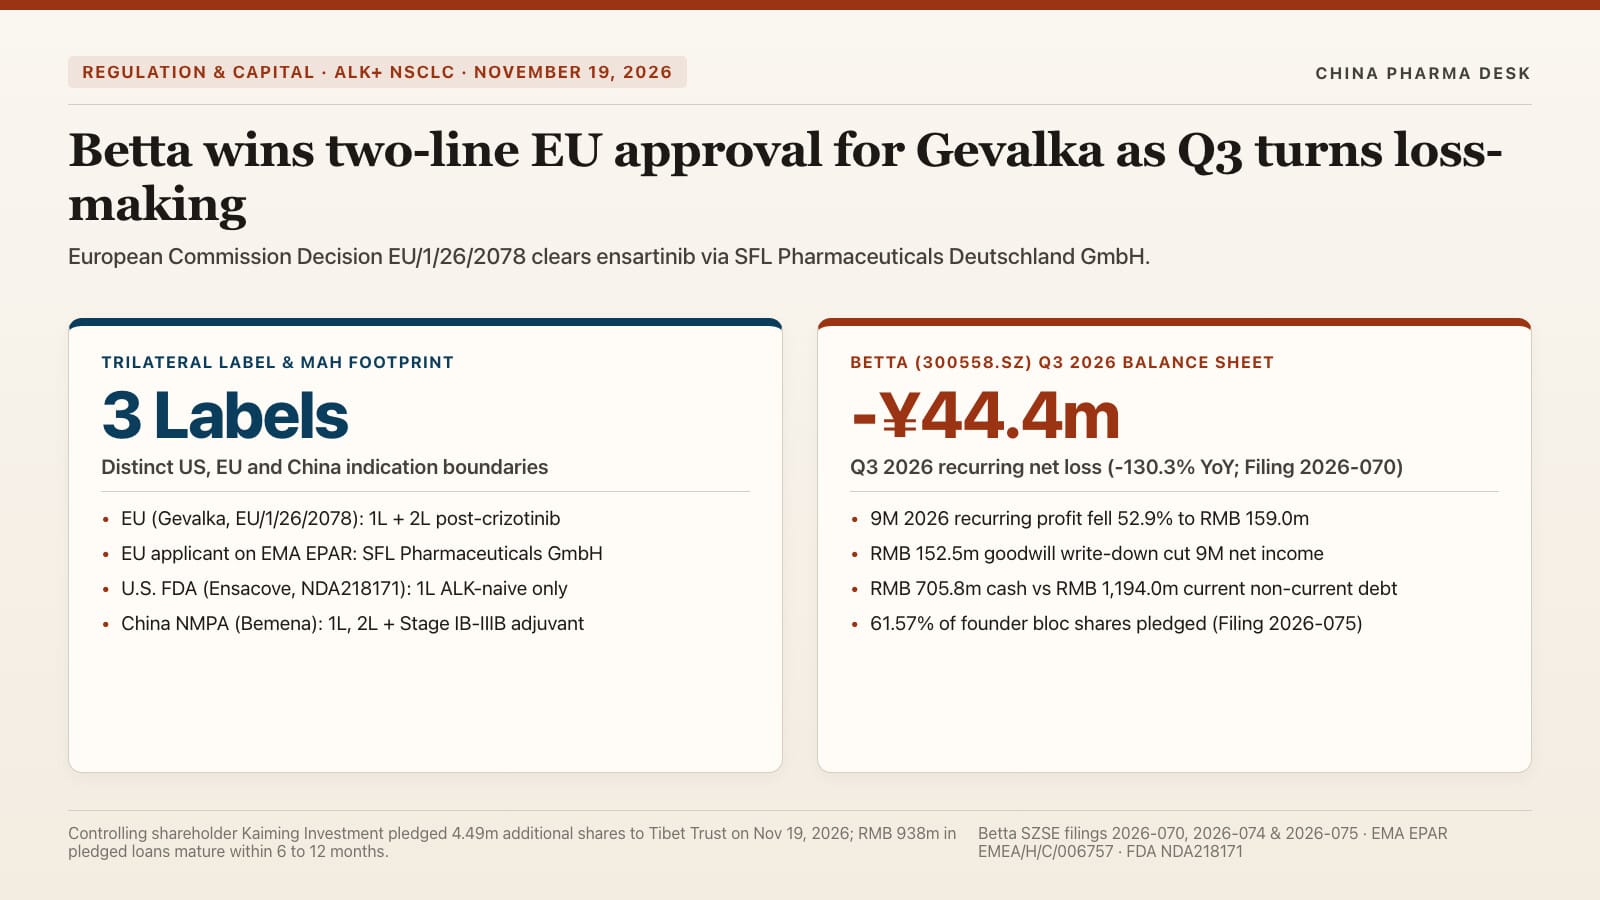
Betta Pharmaceuticals Co., Ltd. (SZSE: 300558) disclosed in Shenzhen Stock Exchange announcement No. 2026-074 (dated November 18, 2026) that the European Commission (EC) has granted marketing authorization (EU/1/26/2078) for its oral anaplastic lymphoma kinase (ALK) inhibitor Gevalka (ensartinib dihydrochloride / X-396, 25 mg and 100 mg capsules) for the treatment of adult patients with ALK-positive advanced non-small cell lung cancer (NSCLC). While the decision makes ensartinib the first Chinese-originated ALK inhibitor approved across China (Bemena, Guoyao Zhunzi H20200009/10), the United States (Ensacove, NDA218171), and the European Union (EMEA/H/C/006757), cross-checking the European Medicines Agency (EMA) European Public Assessment Report (EPAR) overview and Betta’s November 19 share-pledge filing (No. 2026-075) exposes three material operational facts omitted from the headline release: the EU indication covers both first-line and post-crizotinib second-line disease (broader than the U.S. FDA label but narrower than China’s early-stage adjuvant label); the legal EU marketing-authorization applicant on the EMA docket is German regulatory consultancy SFL Pharmaceuticals Deutschland GmbH rather than Betta’s U.S. subsidiary Xcovery Holdings, Inc.; and the approval lands as Betta swung to a Q3 2026 recurring net loss of RMB 44.43 million (approx. $6.15 million) with 61.57% of its controlling shareholder group’s equity pledged against debt.
Three regulators, three different ALK+ NSCLC indication boundaries—and a third-party EU applicant
Following the Committee for Medicinal Products for Human Use (CHMP) positive opinion (EMA/CHMP/205829/2026) adopted on September 17, 2026, European Commission Decision EU/1/26/2078 creates a three-way regulatory split across ensartinib’s global labels:
| Jurisdiction (Brand & Filing ID) | Legal Applicant / MAH on Regulatory Record | Approved Indication Scope | Excluded Settings & Commercial Status |
|---|---|---|---|
European Union (Gevalka, EMEA/H/C/006757 / EU/1/26/2078, Nov 2026) |
SFL Pharmaceuticals Deutschland GmbH (named on EMA EPAR; Betta’s Chinese filing cites subsidiary Xcovery Holdings, Inc.) |
Two lines: (1) 1L monotherapy in ALK-inhibitor-naive advanced NSCLC (eXalt3, NCT02767804); and (2) 2L monotherapy in advanced NSCLC previously treated with crizotinib |
Excludes post-2nd-generation ALK TKI (alectinib/brigatinib) and early-stage adjuvant settings; no European commercial distributor disclosed |
United States (Ensacove, NDA218171, Dec 2024) |
Xcovery Holdings, Inc. (Betta majority-owned U.S. subsidiary) |
One line only: 1L monotherapy in adult ALK+ locally advanced or metastatic NSCLC not previously treated with an ALK inhibitor |
Excludes 2L post-crizotinib and early-stage adjuvant settings; NCCN recommended, but U.S. 1L market dominated by lorlatinib (Lorbrena) and alectinib (Alecensa) |
Mainland China (Bemena, H20200009 / H20200010) |
Betta Pharmaceuticals Co., Ltd. | Three settings: (1) 2L post-crizotinib (Nov 2020); (2) 1L locally advanced/metastatic (Mar 2022); and (3) Stage IB–IIIB post-operative adjuvant therapy (Sept 2026, backed by NEJM July 2026 Phase 3 data showing an 80% reduction in disease recurrence risk) |
Both 1L and 2L metastatic indications are in the basic NRDL (and included as Item #38 on the IAC 58-item commercial insurance list); adjuvant indication missed the June 30, 2026 NRDL cutoff |
Just as we documented on November 17 in IMPACT Therapeutics’ (HKEX: 07630) European filing for the PARP inhibitor senaparib (Sepalna, EMEA/H/C/006708), because EU pharmaceutical law requires a Marketing Authorisation Holder (MAH) to be established inside the European Economic Area (EEA), Florida-based Xcovery Holdings, Inc. could not hold the centralized EU dossier directly in its own name. The EMA EPAR record (EMA/CHMP/205829/2026) lists SFL Pharmaceuticals Deutschland GmbH—the German regulatory-hosting arm of Veristat/SFL—as the formal applicant. Betta’s Announcement No. 2026-074 notes that the company is “actively expanding commercial layouts in emerging markets” but names no European commercial partner or direct sales organization to navigate national Health Technology Assessments (HTA) across EU member states, where Roche’s alectinib (Alecensa) and Pfizer’s lorlatinib (Lorbrena, which posted a 60% 5-year progression-free survival rate in CROWN) already anchor first-line standard of care.
Why European monetization matters: Q3 2026 recurring losses, a RMB 152.5 million goodwill impairment, and a 61.57% founder share pledge
The absence of disclosed ex-China licensing upfronts or European commercial partnerships for Gevalka carries sharper weight when read alongside Betta’s Q3 2026 financial report (Announcement No. 2026-070, filed October 29, 2026) and its November 19, 2026 share-pledge announcement (No. 2026-075):
Financial / Governance Metric (SZSE: 300558, PRC GAAP) |
Q3 2026 (Jul–Sep) | YoY Change | 9M 2026 (Jan–Sep) | YoY Change / Sept 30 Balance |
|---|---|---|---|---|
| Operating revenue | RMB 934.36M (approx. $129.2M) | -5.23% | RMB 2,910.28M (approx. $402.5M) | +7.10% |
| Net income attributable to shareholders | -RMB 23.87M (approx. -$3.3M) | -113.49% | RMB 278.26M (approx. $38.5M) | -12.20% |
Recurring net income/loss (Koufei) |
-RMB 44.43M (approx. -$6.15M) | -130.31% | RMB 158.97M (approx. $22.0M) | -52.86% |
Asset impairment loss (Shangyu Jianzhi goodwill write-down) |
— | — | -RMB 152.46M (approx. -$21.1M) | Goodwill cut 36.86% from RMB 413.58M to RMB 261.12M |
Cash and bank balances (Huobi Zijin) |
— | — | RMB 705.76M (approx. $97.6M) | +64.14% vs. year-end 2025 (RMB 429.98M) |
| Non-current liabilities due within 1 year | — | — | RMB 1,194.03M (approx. $165.1M) | +37.11% vs. year-end 2025 (RMB 870.83M) |
Controlling shareholder bloc share pledge (Filing 2026-075, Nov 19, 2026) |
4,485,800 shares newly pledged to Tibet Trust (1.06% of total capital) | — | 56,034,800 shares pledged (69.99% of Kaiming Investment’s stake; 61.57% of concert party bloc) |
RMB 938.00M (approx. $129.7M) in loans behind 48.52M pledged shares mature within 6–12 months |
Two balance-sheet pressures stand out from those statutory tables:
- Operating margin compression and goodwill write-downs at the corporate level: While Betta’s 9M 2026 revenue edged up 7.10% to RMB 2.91 billion, cost of goods sold rose 35.19% YoY to RMB 722.36 million and accounts receivable jumped 88.73% from year-end to RMB 662.91 million. Combined with a RMB 152.46 million goodwill impairment charge booked in the first nine months of 2026, Q3 recurring net profit swung into a -RMB 44.43 million loss, and cash on hand (
RMB 705.76 million) covers only 59% of theRMB 1,194.03 millionin long-term debt maturing within one year. - Rising leverage at the controlling shareholder entity: On November 19, 2026—one day after disclosing
Gevalka’s EU approval—Betta announced in Filing No.2026-075that its largest shareholder, Ningbo Kaiming Investment Management Partnership (Ningbo Kaiming Investment, holding80,064,000shares or18.91%of the company and acting in concert with Chairman Ding Lieming and Zhejiang Beicheng Investment for a combined21.50%stake), pledged another4,485,800shares to Tibet Trust Co., Ltd. (Tibet Trust) for one year (2026-11-19to2027-11-19) for “own operating needs.” That brings Kaiming Investment’s pledged position to56,034,800shares (69.99%of its direct holdings and61.57%of the controlling concert-party bloc), with48,520,800pledged shares (53.31%of the bloc’s stake) backing RMB 938.00 million (approx. $129.7 million) in financing balances scheduled to mature between May and November 2027.
Three verifiable triggers will determine whether Gevalka’s European approval translates into meaningful cash flow for Betta: whether the EMA Union Register records a Marketing Authorisation transfer from SFL Pharmaceuticals Deutschland GmbH to an European commercial partner (or regional out-licensing deal) following publication of the full Gevalka Summary of Product Characteristics (SmPC); whether Betta submits its Stage IB–IIIB adjuvant ensartinib data to the U.S. FDA or EMA to match its September 2026 Chinese label; and how both Betta (RMB 1.19 billion in current maturing long-term debt) and controlling shareholder Kaiming Investment (RMB 938 million in share-pledge loans maturing in 6–12 months) refinance their 2027 maturities.